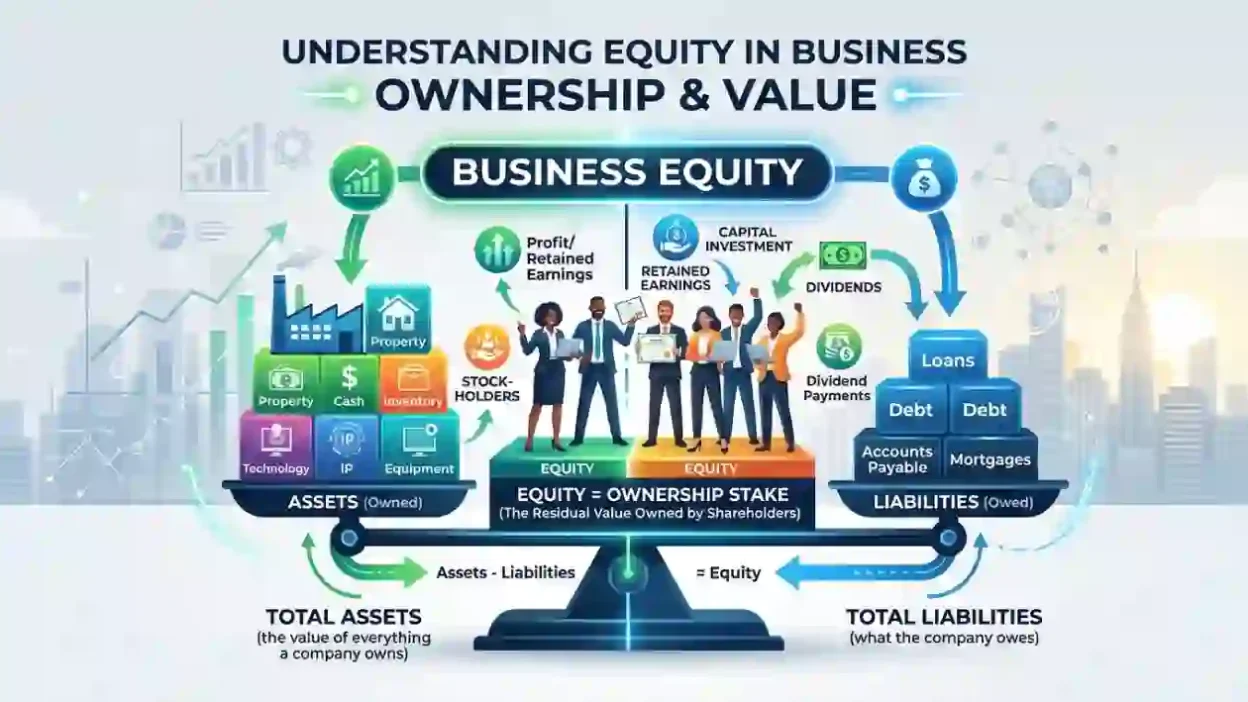
What is equity in business? Equity is the value of an ownership interest in a company after subtracting its liabilities from its assets. It represents the portion of a business that belongs to its owners or shareholders. Equity can increase through profits, investments, and business growth, or decrease through losses and rising liabilities.
Key Takeaways
- Business equity represents the owners’ financial interest in a company.
- You calculate equity by subtracting total liabilities from total assets.
- Equity can come from owner investments, retained earnings, and other sources.
- Business equity differs from debt because it represents ownership rather than borrowed money.
- Equity can help businesses raise capital, attract investors, and measure financial health.
What Is Equity in Business?
Introduction
Understanding business finances can help you make better decisions, whether you own a small business, plan to launch a startup, or want to invest in a company. One important financial term you’ll encounter is equity. It describes the ownership value that remains after a business accounts for everything it owes.
But what is equity in business, and why does it matter? The answer goes beyond simply owning a percentage of a company. Equity helps explain how much financial value belongs to business owners, how investors participate in a company’s growth, and how a business measures its financial position.
In this guide, you’ll learn how business equity works, how to calculate it, and how it differs from debt. You’ll also discover common types of equity, practical examples, and the mistakes to avoid when evaluating a company’s ownership value.
What Does Equity in Business Mean?
Equity in business refers to the financial interest owners have in a company after accounting for its debts and other obligations. It is often called owner’s equity in a sole proprietorship or shareholders’ equity in a corporation.
The basic formula is:
\[ \text{Equity}=\text{Total Assets}-\text{Total Liabilities} \]
Assets include cash, equipment, inventory, buildings, and money customers owe the business. Liabilities include loans, unpaid bills, and other financial obligations.
For example, suppose a small business owns assets worth $200,000 and has liabilities of $75,000. Its equity is $125,000.
Equity is commonly used in financial statements, investment discussions, business sales, startup funding, and company valuation. However, accounting equity does not always equal the price a buyer would pay for the business.
Why Is Equity Important in Business?
Equity helps owners and investors understand how a company is funded and how much value remains after its liabilities are deducted.
Here are some key benefits of understanding equity:
- Measure financial health: Positive equity generally means recorded assets exceed recorded liabilities.
- Attract investors: Companies can sell ownership interests to raise money for growth.
- Track business progress: Profits can increase retained earnings and build equity over time.
- Support lending decisions: Lenders may review equity when assessing a company’s financial position.
- Understand ownership: Equity helps show how ownership is divided among shareholders or partners.
- Plan for the future: Owners can use equity information when considering expansion, selling the business, or bringing in partners.
Equity is only one measure of financial health. A business can have positive equity but still struggle to pay its bills if it lacks available cash.
10 Important Terms Related to Business Equity
These terms explain the different ways equity appears in business accounting, ownership, and investment.
1. Owner’s Equity
Meaning: Owner’s equity is the value of a business that belongs to its owner after liabilities are deducted from assets. It commonly appears in sole proprietorships and certain small-business accounting reports.
Best for: Small-business owners, bookkeeping, and financial reporting.
Example 1: Maria invested $30,000 in her bakery and built additional value through its profits.
Example 2: The accountant reviewed the owner’s equity before preparing the annual financial statements.
Quick Tip: Owner’s equity can change as the owner invests money, withdraws funds, or earns profits.
2. Shareholders’ Equity
Meaning: Shareholders’ equity represents the portion of a corporation’s accounting value attributable to its shareholders. It can include contributed capital, retained earnings, and other equity accounts.
Best for: Corporate accounting, investors, and financial analysis.
Example 1: Investors reviewed the company’s shareholders’ equity before comparing its annual reports.
Example 2: Higher retained earnings contributed to an increase in the corporation’s equity.
Quick Tip: Look at shareholders’ equity alongside debt, earnings, and cash flow rather than treating it as a complete measure of performance.
3. Ownership Interest
Meaning: Ownership interest describes a person’s legal or economic stake in a business. Depending on the business structure and agreement, it may provide rights to profits, voting, or a share of proceeds when the business is sold.
Best for: Business partnerships, company formation, and ownership agreements.
Example 1: Daniel received a 25% ownership interest when he joined the partnership.
Example 2: The founders discussed ownership interests before accepting outside funding.
Quick Tip: Confirm the rights attached to an ownership interest; the percentage alone may not explain every decision-making or financial right.
4. Share Capital
Meaning: Share capital generally refers to the capital a corporation receives through issuing shares, as recorded under applicable accounting rules. It represents part of the shareholders’ investment in the company.
Best for: Corporate finance, accounting, and investment discussions.
Example 1: The company issued additional shares to fund a new production facility.
Example 2: The accountant recorded the share issuance in the corporation’s financial records.
Quick Tip: Share capital is only one component of shareholders’ equity, not the company’s total equity.
5. Retained Earnings
Meaning: Retained earnings are accumulated profits that a company has kept rather than distributed to shareholders as dividends. Losses and dividend payments can reduce this balance.
Best for: Profit analysis, corporate accounting, and growth planning.
Example 1: The company used its retained earnings to expand into another state.
Example 2: Management decided to reinvest profits instead of paying a larger dividend.
Quick Tip: Retained earnings do not necessarily mean the company has the same amount of cash available in its bank account.
6. Equity Financing
Meaning: Equity financing involves raising money by giving investors an ownership stake in a business. Unlike a typical loan, the investment generally does not require scheduled principal repayments, but it can dilute existing owners’ percentage interests.
Best for: Startups, expansion plans, and fundraising.
Example 1: The startup raised $500,000 through equity financing to develop its software.
Example 2: The founders compared equity financing with a business loan before choosing how to fund expansion.
Quick Tip: Consider dilution, investor rights, and long-term ownership implications before issuing shares.
7. Net Worth of a Business
Meaning: Business net worth is a common way to describe the difference between total assets and total liabilities. In a standard balance-sheet context, this is closely related to accounting equity.
Best for: Financial reviews, business planning, and basic valuation discussions.
Example 1: The owner calculated the company’s net worth before meeting with a financial adviser.
Example 2: The business’s net worth increased after it paid down debt and retained profits.
Quick Tip: Specify whether you mean accounting net worth or market value because the two figures can differ.
8. Equity Stake
Meaning: An equity stake is the ownership share held by an individual or organization in a business. It may be expressed as a percentage or represented by a specific number and class of shares.
Best for: Investor agreements, startups, and partnership discussions.
Example 1: The investor negotiated a 10% equity stake in the new company.
Example 2: The founders reviewed how the proposed investment would change each person’s equity stake.
Quick Tip: Check the fully diluted ownership calculation, share classes, and contractual rights before comparing equity stakes.
9. Book Value
Meaning: Book value is an accounting-based measure derived from recorded assets and liabilities. For a company, total shareholders’ equity is often described as its book value, although specific calculations may adjust for preferred shares or other items.
Best for: Financial statements and company comparisons.
Example 1: The analyst compared the company’s book value with its market capitalization.
Example 2: A large asset write-down reduced the business’s reported book value.
Quick Tip: Book value depends on accounting records and may not reflect the current market value of every asset.
10. Equity Capital
Meaning: Equity capital is money contributed to a business by its owners or investors in exchange for an ownership interest. Companies may use it to launch operations, purchase equipment, hire employees, or support expansion.
Best for: Business funding, corporate finance, and investment planning.
Example 1: The founders provided equity capital to open their first retail location.
Example 2: The company raised equity capital to support its product launch.
Quick Tip: Evaluate the ownership and control implications of new equity capital alongside the amount of funding received.
Comparison Table: Types of Business Equity
| Alternative | Best Used In | Tone |
|---|---|---|
| Owner’s equity | Small-business accounting | Practical |
| Shareholders’ equity | Corporate financial reports | Formal |
| Ownership interest | Partnerships and legal agreements | Professional |
| Share capital | Corporate accounting | Technical |
| Retained earnings | Profit and growth analysis | Financial |
| Equity financing | Fundraising and investment | Professional |
| Net worth of a business | Financial assessments | General |
| Equity stake | Investor negotiations | Business-focused |
| Book value | Financial analysis | Technical |
| Equity capital | Business funding | Professional |
How to Calculate Equity in Business
Calculating business equity is straightforward when you know the value of the company’s assets and liabilities.
Follow these three steps:
- Add total assets. Include cash, accounts receivable, inventory, equipment, property, and other recognized assets.
- Add total liabilities. Include loans, accounts payable, accrued expenses, and other recorded obligations.
- Subtract liabilities from assets. The remaining amount represents the business’s accounting equity.
For example, consider a business with these financial figures:
| Financial Item | Amount |
|---|---|
| Total assets | $350,000 |
| Total liabilities | $140,000 |
| Business equity | $210,000 |
The calculation is $350,000 − $140,000 = $210,000.
This means the business has $210,000 in accounting equity. It does not necessarily mean the owner could sell the company for that exact amount because market demand, future earnings, brand value, and other factors can affect the selling price.
Common Mistakes When Understanding Business Equity
Avoid these five mistakes when reviewing equity or explaining it to others.
1. Confusing equity with cash. Equity measures the difference between assets and liabilities. A business may have substantial equity tied up in property or equipment but little cash available for immediate expenses.
2. Treating equity as company market value. Accounting equity comes from recorded financial amounts, while market value reflects what buyers or investors may be willing to pay.
3. Ignoring liabilities. Looking only at a company’s assets can create an incomplete picture. Loans, unpaid bills, and other obligations must also be considered.
4. Assuming positive equity guarantees financial stability. A business can have positive equity and still face cash-flow problems, missed payments, or falling sales.
5. Overlooking ownership dilution. When a company issues new shares, existing shareholders may own a smaller percentage of the business, even if the company’s total value increases.
Frequently Asked Questions
1. What is equity in business in simple words?
Equity is the portion of a business’s value that remains after subtracting its debts and other liabilities from its assets. It helps show the owners’ financial interest in the company. For example, if a business has $100,000 in assets and $40,000 in liabilities, its accounting equity is $60,000.
2. How do you calculate equity in a business?
Use the formula: Equity = Total Assets − Total Liabilities. First, calculate the value of all recognized business assets. Then subtract all recorded liabilities. If assets total $250,000 and liabilities total $90,000, the business has $160,000 in equity.
3. What is a good equity percentage for a business?
There is no single ideal equity percentage for every business. The appropriate level depends on the industry, cash flow, business maturity, asset requirements, and debt obligations. Comparing equity with total assets can help assess capitalization, but it should be considered alongside liquidity, profitability, and debt levels.
4. What is the difference between equity and debt?
Equity represents ownership in a business, while debt represents money the business must repay under agreed terms. Equity investors may benefit from profits and business growth, but they also bear investment risk. Debt generally requires repayment and may involve interest, but it does not automatically give lenders an ownership stake.
5. Can a business have negative equity?
Yes. A business has negative equity when its recorded liabilities exceed its recorded assets. This can happen after repeated losses, large write-downs, or significant debt accumulation. Negative equity can signal financial pressure, but its implications depend on the company’s cash flow, business model, obligations, and plans for recovery.
6. How does equity work in a startup?
Startup equity represents the ownership held by founders, employees with equity awards, and investors. Founders may exchange a percentage of ownership for funding or strategic support. When new shares are issued, existing owners may experience dilution. Ownership percentages, voting rights, vesting schedules, and investment terms all affect how startup equity works.
7. Is equity the same as profit?
No. Profit is the amount left from revenue after expenses are deducted over a particular period. Equity is a balance-sheet measure of the owners’ interest at a specific point in time. Profits that remain in the business can increase equity, but losses, distributions, and other transactions can change it as well.
8. Why do investors look at shareholders’ equity?
Investors review shareholders’ equity to understand a company’s recorded financial position and how much value remains after liabilities. They may compare it with debt, earnings, return on equity, and market capitalization. However, equity alone cannot determine whether a stock is a good investment; future performance, risk, and valuation also matter.
Conclusion
Understanding what is equity in business helps you make smarter decisions about ownership, funding, and financial performance. Equity represents the difference between a company’s total assets and total liabilities, giving owners and investors a useful view of its accounting value.
The right equity term depends on your situation. Small-business owners often use owner’s equity, while corporations report shareholders’ equity. Entrepreneurs raising funds may discuss equity financing or an equity stake, and financial analysts may examine book value or retained earnings.
Remember that equity is not the same as cash, profit, or market value. A company can have strong equity and still face cash-flow challenges, so always consider its broader financial position.